This content has been updated from the previous article published on April 7, 2026.
Earned Wage Access (EWA) has become one of the most widely discussed payroll and financial wellness benefits in the modern workplace. As employers look for ways to support employee financial flexibility while modernizing payroll systems, many are evaluating EWA platforms as part of a broader workforce strategy.
Over the past several years, the EWA landscape has expanded rapidly. What began primarily as a payroll feature allowing employees to access wages before payday has evolved into a range of solutions, including payroll-integrated tools, direct-to-consumer apps, and platforms that may include additional financial features.
As a result, employers evaluating EWA providers are often comparing platforms with very different capabilities and operating models.
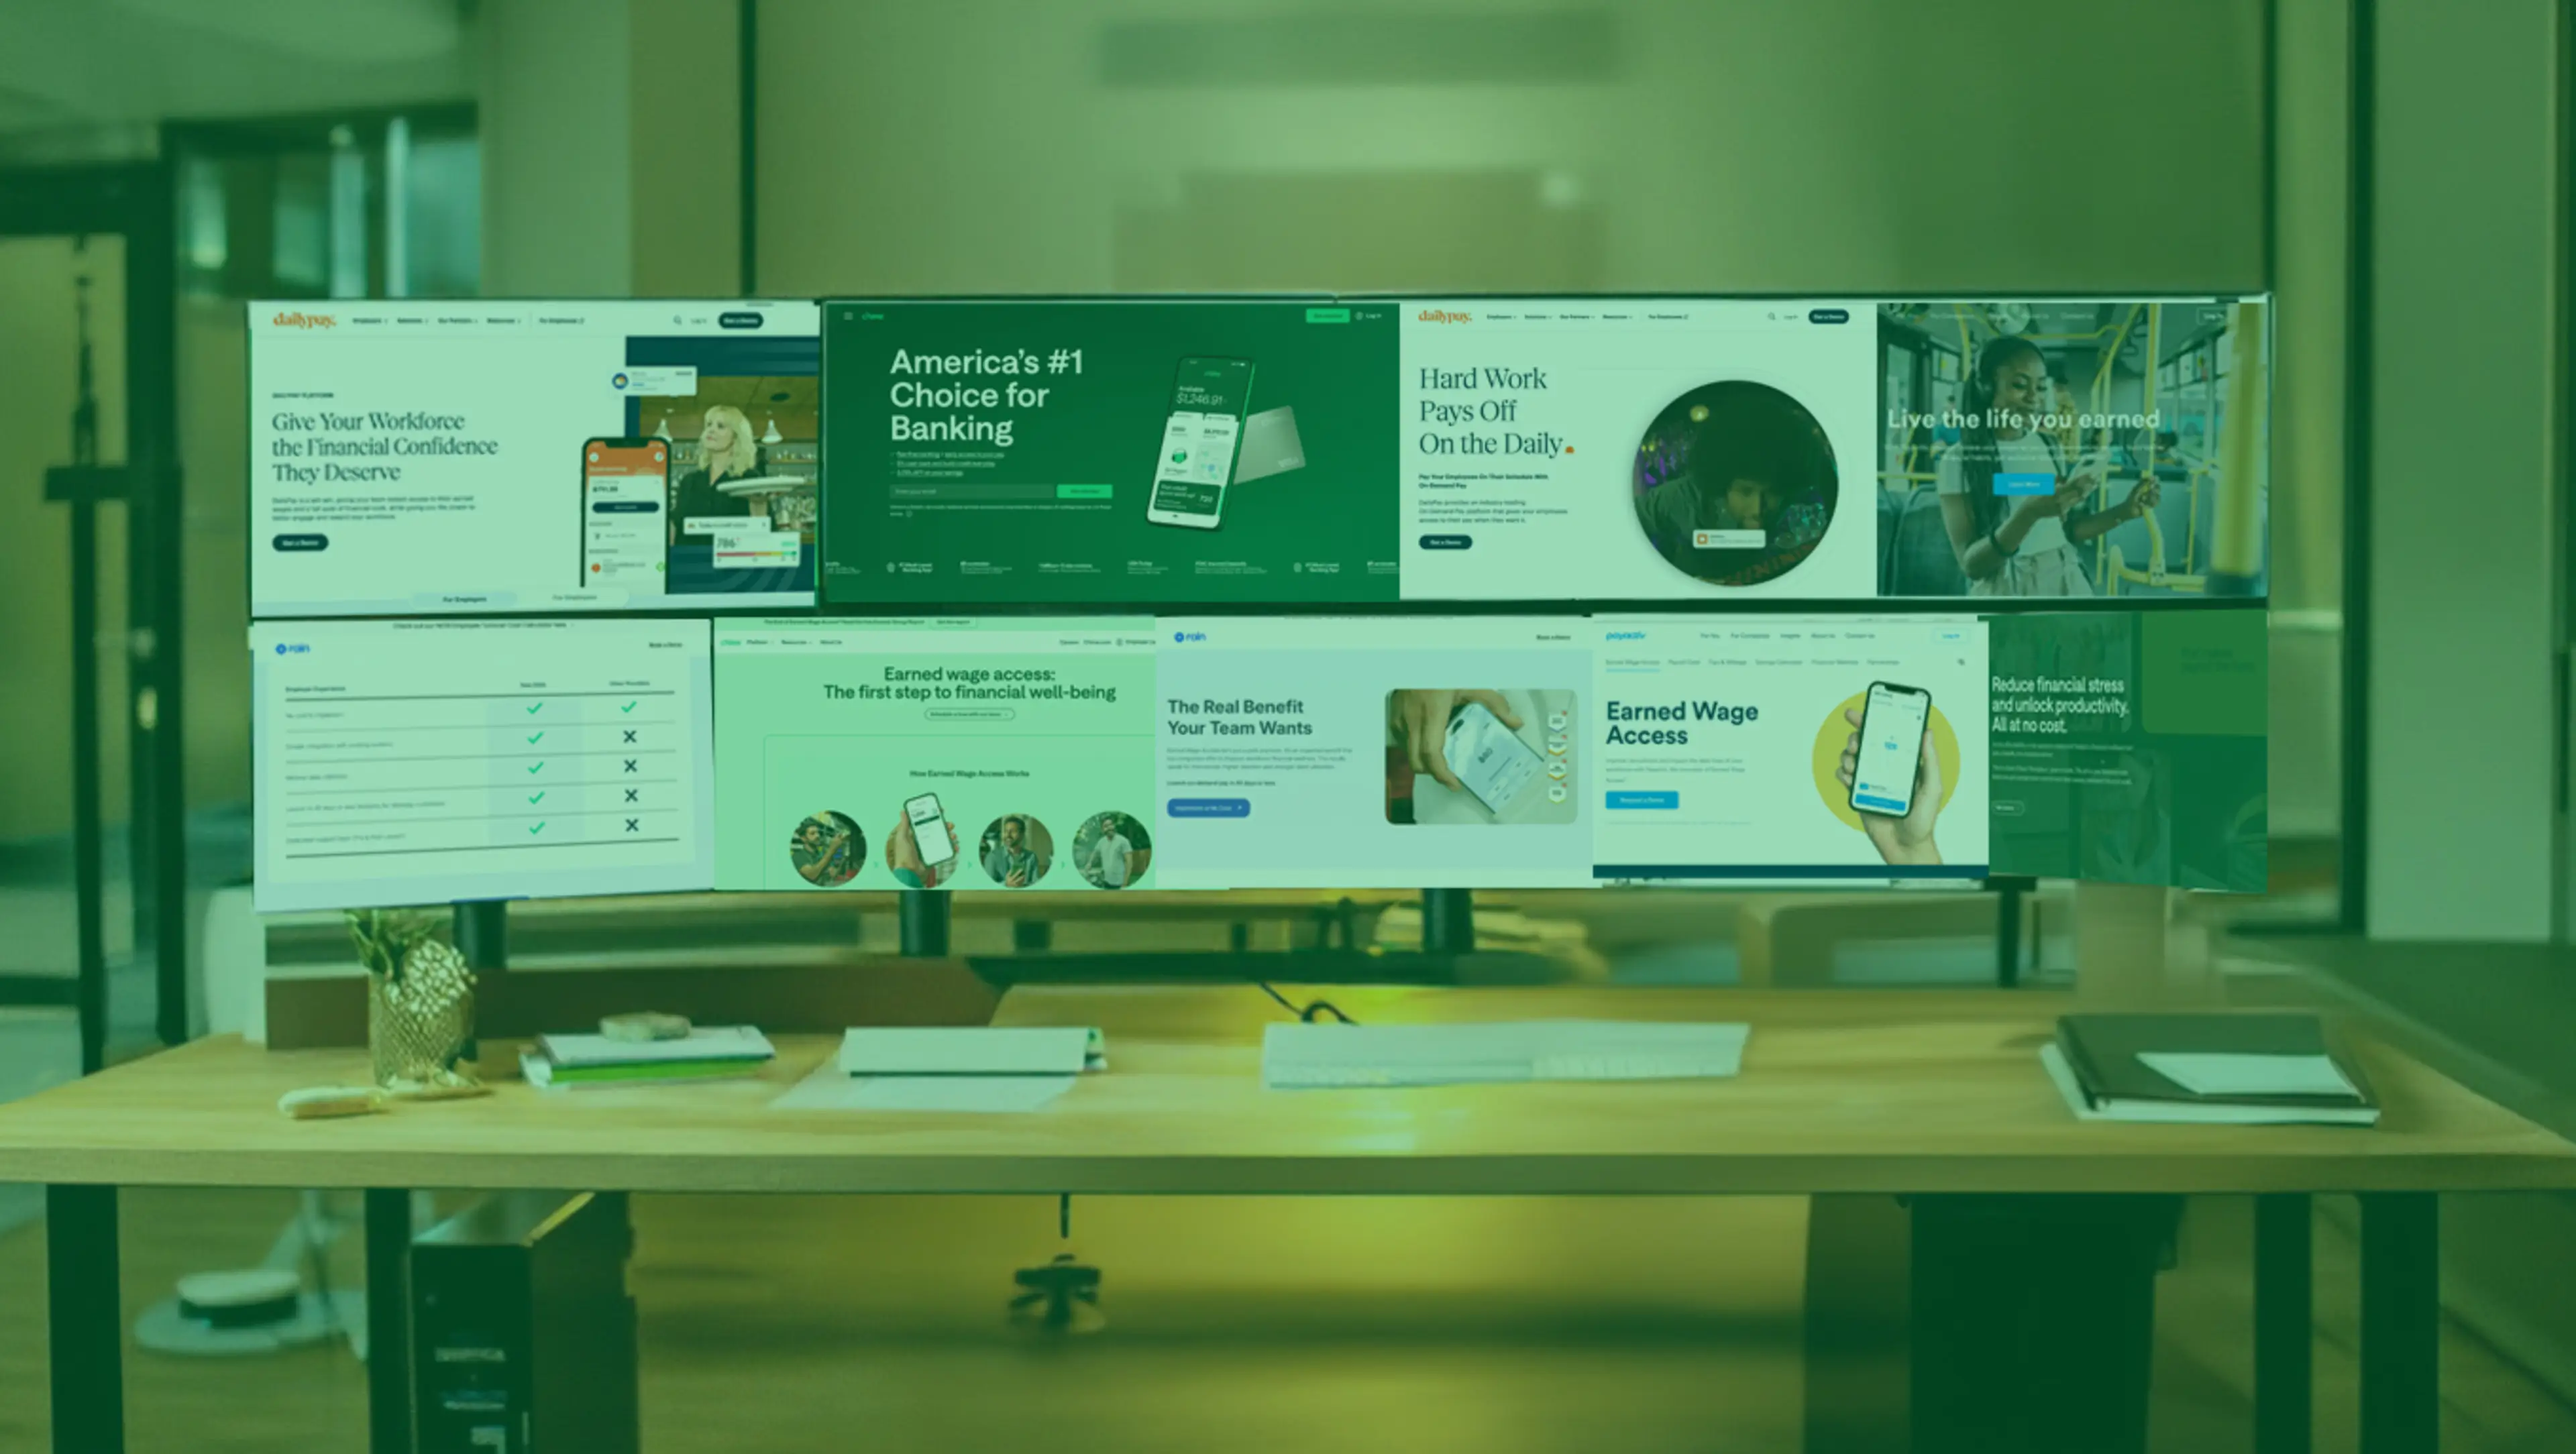
This guide reviews several widely used Earned Wage Access providers operating in 2026, including:
Branch®
Chime Workplace™
DailyPay®
Earnin®
Payactiv®
Rain®
Stream®
Tapcheck®
ZayZoon®
To help employers navigate these differences, this guide compares providers using common criteria considered during procurement processes, including employee fee structures, repayment models, payroll integration complexity, and the availability of broader financial wellness tools.
Best Earned Wage Access Providers Compared
The following table provides a high-level overview of how several leading EWA platforms approach key structural components of their solutions.
Provider | Repayment Model | Fee Model | Financial Wellness Tools‡‡ |
Branch® | Payroll deduction | Up to $4.99 per instant transfer* | Basic |
Chime Workplace™ | Settlement model | Fee-freea | Advanced |
DailyPay® | Payroll intercept | $3.49 per instant transfer† | Basic |
Earnin® | Third party debiting | Up to $5.99 per instant transfer plus optional tips‡ § | Basic |
Payactiv® | Payroll deduction | Up to $3.49 per instant transfer ‖ | Standard |
Rain® | Payroll deduction | $3.99 per instant transfer (fees may vary)¶ | Basic |
Stream® | Payroll intercept typically (may vary) | $3.29 per instant transfer# | Standard |
Tapcheck® | Payroll deduction | $4.95 per instant transfer** | Basic |
ZayZoon® | Payroll deduction | $5.00 per instant transfer†† | Basic |
*Branch Terms and Conditions, last revised October 2023.
aMyPay at Work™ advances are instant and free while you are employed with a Participating Employer.
† "Earned Wage Access Explained: Benefits and Regulations," DailyPay, as of August 2026.
‡ "Lightning Speed fees and details,"Earnin Terms of Service, as of August 2026.
§ Balance Shield, EarnIn, as of August 2026.
‖ Program Pricing, Payactiv, June 2026.
¶ "On Demand Pay," Rain, as of August 2026.
# "Stream vs Rain: Earned Wage Access & Benefits Comparison," Stream, January 2026.
** "Tapcheck: Pricing, Free Demo & Features," Software Finder, August 2026.
†† "Get Paid Today | Time and Pay & ZayZoon," ZayZoon, as of August 2026.
‡‡Based on publicly available features; scope and availability may vary by employer configuration. Basic, standard and advanced are defined as follows: Basic includes one of the following: (i) high yield savings, (ii) credit building & monitoring and (iii) financial education (i.e. coaching, goals tracking, and/or budgeting). Standard includes two of the following: (i) high yield savings, (ii) credit building & monitoring and (iii) financial education (i.e. coaching, goals tracking, and/or budgeting. Advanced includes three of the following: (i) high yield savings, (ii) credit building & monitoring and (iii) financial education (i.e. coaching, goals tracking, and/or budgeting)
While these platforms operate within the same general category, their approaches vary significantly—from focused wage access tools to broader financial platforms designed to support employees’ long-term financial well-being.
What Is Earned Wage Access (EWA)?
Earned Wage Access, also referred to as on-demand pay or early pay access, allows employees to access a portion of wages they have already earned before their scheduled payday. Instead of waiting for a traditional payroll cycle, employees can request access to accrued earnings through a mobile application or payroll-integrated platform.
In many cases, the available amount is calculated based on hours worked or wages accrued within a pay period. The funds are then reconciled when payroll runs.
EWA programs can be delivered in several ways. Some operate directly through employer payroll integrations, while others function as consumer financial apps connected to employee bank accounts.
For many organizations, earned wage access is increasingly considered part of a broader financial wellness strategy designed to support employees experiencing short-term financial challenges between paychecks.
What Employers Should Look for in an EWA Provider
Earned Wage Access programs can differ significantly in structure, cost, and implementation. Employers evaluating providers often consider several operational and employee-experience factors.
1. Employee Fee Structures
One of the most visible differences between EWA providers is whether and how employees are charged for accessing earned wages.
Some platforms rely on employees paying:
Optional instant transfer fees
Monthly subscription fees
Per-transaction charges
Employer-paid program structures
Tip-based pricing models
While EWA providers often offer free options like overnight ACH transfers, workers usually pay fees for instant access anyway. The CFPB reported that 9 out of 10 workers using EWA paid a fee, at an average of $3.18 per transfer.1 According to the New York Attorney General, those fees can add up to an average of $370 per year for workers using a popular EWA app.2
Recently, a truly no-free model has emerged. Banking platforms, because they have alternative sources of revenue like merchant-funded interchange, can now offer instant access at no cost. Independent research analyst Everest Group has called this fee-free model the future of EWA.
2. Payroll Integration and Implementation
Employers often prioritize solutions that integrate with existing payroll or HR systems.
Common integrations include:
ADP®
UKG®
Paychex®
Integration depth can influence implementation timelines, payroll complexity, and employee eligibility verification.
Some EWA providers operate primarily as employer-integrated payroll tools, while others function independently of employer systems.
3. Repayment Models
Another major point of differentiation is how funds accessed by employees are reconciled.
Most EWA platforms rely on one of three repayment structures.
Deduction Model, where the employer deducts the amount of the advance already taken (plus any applicable fees) from the worker’s paycheck and sends the repayment directly to the EWA provider.
Payroll Intercept Model, in which the employer sends the entire paycheck to the EWA provider, who repays itself for the advance already taken (plus any applicable fees) before distributing the remaining pay to the employee.
Settlement Model, where the employer sends the entire paycheck to the worker’s bank account as usual, then settlement occurs from the bank account at the direction of the employee.
Each model has different operational, compliance, and administrative considerations. Employers typically evaluate these approaches based on payroll workflows, regulatory requirements, implementation complexity, and employee experience. The Deduction and Payroll Intercept Models require a change to the payroll process and thus introduce potential operational and legal risks, especially in states with wage assignment or improper wage deduction statutes.
4. Financial Wellness Capabilities
Early EWA platforms focused primarily on wage access functionality.
More recently, some providers have expanded into broader financial ecosystems that may include tools such as:
Savings accounts
Credit-building capabilities
Budgeting tools
Financial education resources
For employers building long-term financial wellness programs, these additional capabilities may play an important role in provider selection.
Leading Earned Wage Access Providers
The providers below illustrate how these differences appear in practice. While each platform operates within the earned wage access category, their approaches vary—from focused wage access tools to broader financial platforms.
Providers are listed in alphabetical order.
Branch®
Branch focuses on workforce payments infrastructure, combining digital payment accounts with wage access functionality. The platform is often used by employers seeking tools for wage disbursement alongside employee payment accounts.
Repayment model
Payroll deduction model through employer integrations.
Has
Workforce payment accounts
Debit card infrastructure
Payroll-integrated wage access
Branch’s approach centers on workforce payments rather than financial wellness services.
Chime Workplace™
Chime Workplace™ is structured as a financial wellness platform that includes fee-free earned wage access as part of a broader employee financial ecosystem.
Rather than offering wage access as a standalone feature, the platform integrates EWA alongside several tools designed to support employees’ financial lives.
Repayment model
Settlement model that enables repayment in the bank account, not as a payroll deduction
Has
Employer-integrated fee-free instant wage access
Additional financial tools such as savings and credit-building features, fee-free overdraft features, and early direct deposit.
Workforce financial progress reporting
Payroll integrations
Because wage access is integrated into a broader set of financial tools, the platform may appeal to employers exploring financial wellness programs alongside pay access solutions.
DailyPay®
DailyPay is an employer-integrated earned wage access platform that connects directly with payroll systems to allow employees to access earned wages before payday.
Repayment model
Payroll Intercept model where the employer sends the entire paycheck to DailyPay, which repays itself before sending residual pay to the employee.
Has
Employer-integrated wage access
Instant access options
Payroll system integrations
Enterprise reporting tools
DailyPay’s model focuses primarily on delivering wage access functionality within payroll infrastructure.
Earnin®
Earnin operates primarily as a direct-to-consumer earned wage access application rather than an employer-sponsored benefit.
Employees connect their bank accounts and employment data directly to the app to access wages independently of employer payroll systems.
Repayment model
Third party debiting model (ACH debit from the employee’s bank account).
Has
Direct-to-consumer wage access
Optional tip-based pricing
Instant transfer capability
Because Earnin typically operates independently from employers, it is positioned primarily as a direct-to-consumer solution rather than an employer-sponsored benefit.
Payactiv®
Payactiv is one of the earlier employer-sponsored EWA providers and offers wage access alongside additional financial services.
The platform is commonly deployed as an employee benefit through employer payroll systems.
Repayment model
Payroll deduction model.
Has
Employer-integrated wage access
Financial education resources
Payroll integrations
Rain®
Rain provides a payroll-integrated earned wage access solution designed for mid-market and enterprise employers. The platform emphasizes payroll-native integration and relatively straightforward implementation.
Repayment model
Payroll deduction model.
Has
Payroll-integrated wage access
Employer implementation model
Stream®
Stream partners with employers to provide earned wage access and other financial tools. It offers other financial wellness and educational tools.
Repayment model
Payroll intercept model, typically (may vary).
Has
Payroll-integrated wage access
Workplace savings
Credit score tracking
Tapcheck®
Tapcheck provides employer-integrated wage access programs often used in industries with shift-based employment such as healthcare and service sectors.
Repayment model
Payroll deduction model.
Has
Employer payroll integration
Instant wage access option (fees may apply)
Employee mobile access
ZayZoon®
ZayZoon primarily targets small and mid-sized businesses with an earned wage access offering combined with financial education resources.
Repayment model
Payroll deduction model.
Has
Employer-integrated wage access
Financial education tools
SMB-focused deployment model
Key Differences Between EWA Platforms
While all earned wage access platforms provide access to wages before payday, their approaches can vary significantly.
Some providers focus on wage access functionality, while others include additional financial tools. The relevance of these features depends on employer priorities and workforce needs.
These differences may influence how organizations evaluate providers depending on their priorities.
Employers seeking a simple payroll feature may prioritize platforms that integrate directly into payroll workflows. Others may view EWA as part of a broader financial wellness initiative designed to support employees’ financial resilience over time.
Understanding these distinctions can help organizations evaluate which model best aligns with their workforce strategy. Learn more by booking a demo with Chime Workplace today!
Disclosures
Providers are included for informational comparison only and are not ranked.
1 Data Spotlight, CFPB (2024)
2 NY Attorney General, State of New York v. DailyPay, Verified Petition (2025)